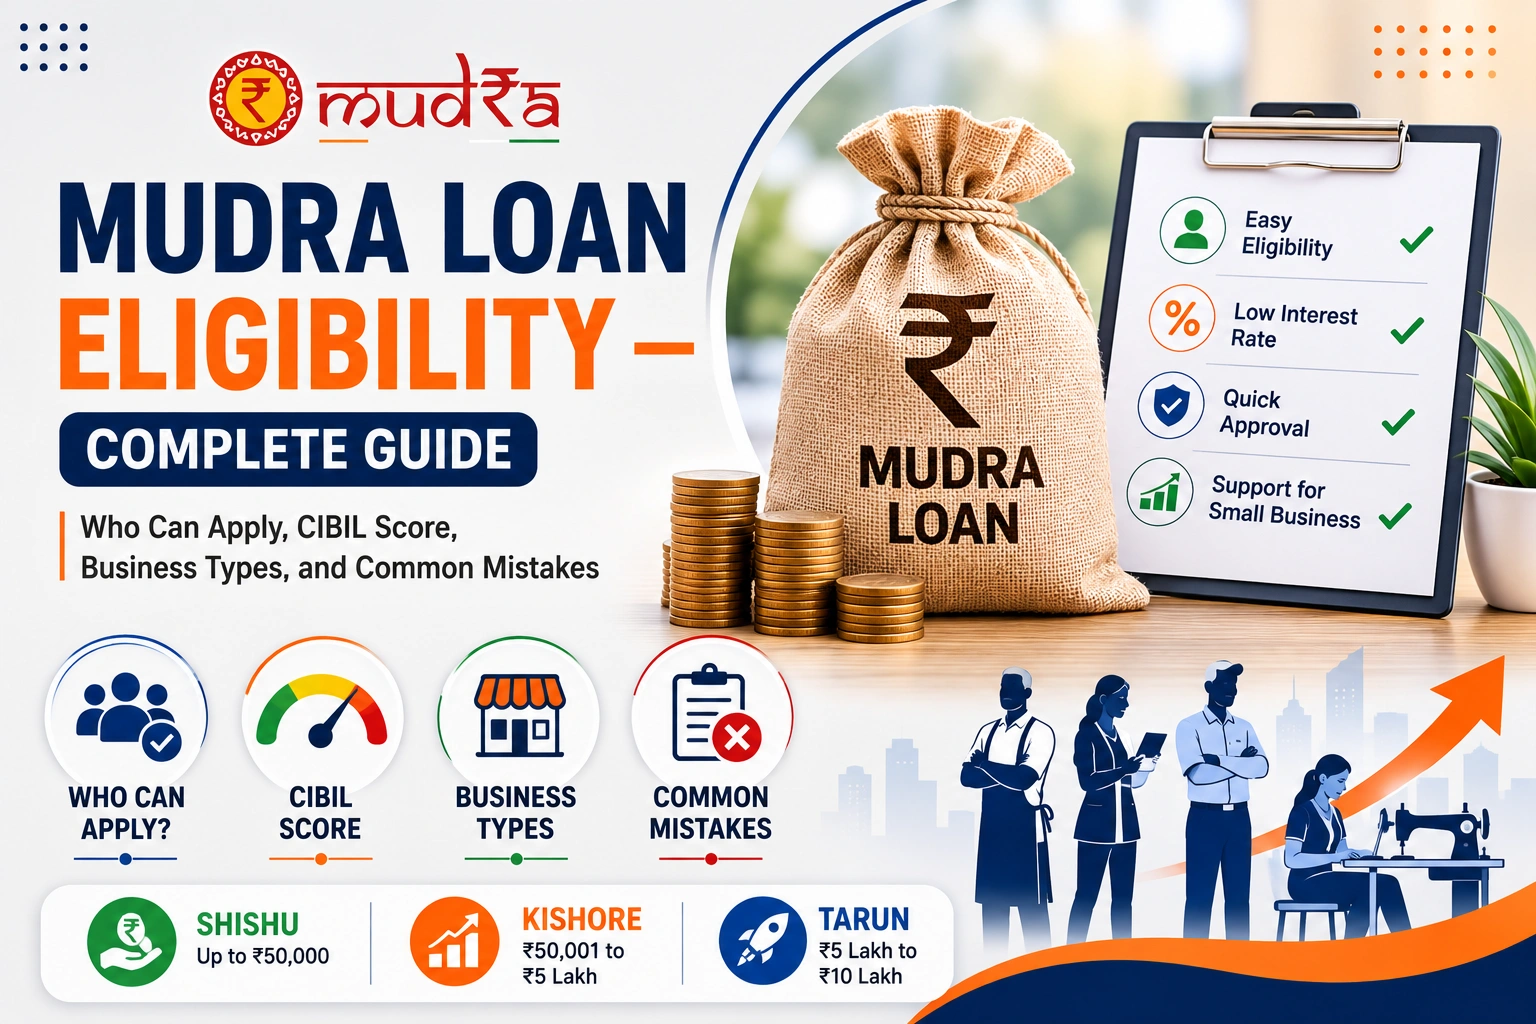
Mudra Loan Eligibility 2026 — Complete Guide: Who Can Apply, CIBIL Score, Business Types, and Common Mistakes
Quick Answer — Mudra Loan Eligibility 2026 To be eligible for a Mudra loan in 2026, you must be an [ ]
Quick Answer — Mudra Loan Eligibility 2026
To be eligible for a Mudra loan in 2026, you must be an Indian citizen aged 18 to 65, running or planning to run a non-farm, non-corporate business in manufacturing, trading, or services. You must have no active loan defaults with any bank or financial institution. There is no officially mandated minimum CIBIL score — but practically, 650 and above significantly improves approval chances. Agriculture-allied businesses like dairy, poultry, food processing, and fisheries are eligible; pure crop farming is not. The Mudra loan limit in 2026 is Rs.20 lakh under the Tarun Plus category, introduced in Union Budget 2024-25. A strong project report is mandatory for Kishore and Tarun categories.
Source: PMMY Official Guidelines — mudra.org.in | PIB — pib.gov.in
Key Takeaways
✅ Age 18-65, Indian citizen, non-farm business — these three are the absolute base criteria; everything else is assessed at the bank level
✅ No official minimum CIBIL score under PMMY — but 650 and above is the practical threshold; no credit history at all (score -1 or 0) is acceptable with a clean bank record for Shishu
✅ 52 crore+ loan accounts disbursed since 2015, Rs.32 lakh crore total — the scheme is real, active, and widely accessible; the bottleneck is preparation, not eligibility
✅ Tarun Plus (Rs.10-20 lakh) has stricter eligibility — only for entrepreneurs who have already fully repaid a previous Tarun loan; first-time borrowers max out at Rs.10 lakh under Tarun
✅ Both new startups and existing businesses are eligible — Shishu for first-time entrepreneurs, Kishore and Tarun for expanding established units; no income ceiling, no mandatory income proof for smaller amounts
Table of Contents
Meera Joshi's Story — Eligible All Along, Just Didn't Know It
Meera Joshi, 34, from Nashik, Maharashtra, had spent six years working in a stitching workshop. When she decided to start her own tailoring unit, the first question she had was the one most people ask: "Will I even get a loan?"
She had no CIBIL score — she had never taken any loan before. She had no CA account, no ITR filed. Her business was running from a single room at home, with no trade license.
Three different bankers gave her three different answers.
The SBI branch manager told her she needed a CIBIL score. A private NBFC asked for Rs.5,000 in processing fees before even reviewing her application. A local agent offered guaranteed approval for Rs.8,000 upfront.
All three were wrong.
The official PMMY eligibility criteria does not mandate a minimum CIBIL score. No credit history — a score of -1 — is still acceptable for Shishu. A home-based business is allowed. ITR is not mandatory for loans under Rs.2 lakh at most banks.
Meera registered on Udyam for free, built her project report through MudraReady for Rs.399, and walked into Bank of Baroda with a complete file. The loan — Rs.3 lakh Kishore — was approved in 19 days.
Today her tailoring unit in Nashik's Panchavati area employs three people. Monthly revenue is Rs.85,000. The EMI is Rs.6,500. Comfortable.
The problem was never eligibility. It was information.
What Is a Mudra Loan — A 60-Second Recap
PMMY = Pradhan Mantri Mudra Yojana
Launched: April 8, 2015 Purpose: "Fund the Unfunded" — collateral-free credit for micro and small businesses Implementing body: MUDRA (Micro Units Development & Refinance Agency), a SIDBI subsidiary Disbursed through: Public sector banks, private banks, RRBs, Small Finance Banks, NBFCs, MFIs
MUDRA does not lend directly. It refinances lending institutions, which then give loans to borrowers.
Four Categories in 2026:
| Category | Loan Amount | Intended For |
|---|---|---|
| Shishu | Up to Rs.50,000 | New businesses, first-time entrepreneurs |
| Kishore | Rs.50,001 to Rs.5 lakh | Established businesses needing expansion capital |
| Tarun | Rs.5,00,001 to Rs.10 lakh | Scaling businesses with higher capital needs |
| Tarun Plus | Rs.10,00,001 to Rs.20 lakh | Proven Tarun borrowers with clean repayment record only |
Mudra Loan Eligibility — Complete Criteria 2026
1. Age
Minimum: 18 years Maximum: 65 years — no official upper limit under PMMY, but most banks prefer applicants below 65 to ensure adequate repayment capacity
2. Citizenship
Must be an Indian citizen. NRIs are not eligible under PMMY.
3. Business Type — What Is Eligible
| Sector | Examples |
|---|---|
| Manufacturing | Agarbatti, flour mill, garment unit, furniture, paper products, metal fabrication, soap |
| Trading | Grocery store, hardware shop, wholesale, retail, stationery |
| Services | Beauty parlour, tailoring, mobile repair, coaching centre, catering, transport |
| Agriculture-Allied | Dairy farming, poultry, fishery, beekeeping, food processing, agro-processing |
| Artisans and Craftsmen | Pottery, handloom, weaving, carpentry, embroidery |
| Street Vendors | Fruit and vegetable vendors, roadside stalls, hawkers |
| Transport | Auto-rickshaw, e-rickshaw, small goods vehicle, delivery business |
4. Business Structure — Who Can Apply
| Entity Type | Eligible |
|---|---|
| Individual / Sole Proprietor | Yes |
| Partnership Firm | Yes |
| LLP (Limited Liability Partnership) | Yes |
| Private Limited Company | Yes — if micro or small enterprise |
| Self Help Group (SHG) | Yes |
| NGO / Trust | Yes — for income-generating activities |
| Cooperative Society | Yes |
| Large Corporate or Public Limited Company | No |
5. Loan Default Status
No active defaults with any bank, NBFC, or financial institution. Even a small default — a Rs.2,000 credit card payment or Rs.5,000 consumer loan — can cause rejection at the bank level. Check and clear all defaults before applying.
6. Business Stage
- New business: Eligible — Shishu is specifically designed for startups and first-time borrowers
- Existing business: Eligible — Kishore and Tarun are for expansion of existing units
- Home-based business: Eligible — your residential address can serve as the business address
CIBIL Score — The Official Rule vs the Practical Reality
This is where most applicants get confused. The distinction matters.
Official PMMY rule: No minimum CIBIL score is mandated.
Practical reality at bank branches in 2026:
| CIBIL Score | What Typically Happens | Best Bank Type to Approach |
|---|---|---|
| 750 and above | Smooth approval, best interest rates, fast processing | Any PSU or private bank |
| 700 to 749 | Good approval chances, standard terms | SBI, Bank of Baroda, PNB |
| 650 to 699 | Possible but with extra scrutiny — strong project report helps | PSU banks |
| 600 to 649 | Most PSU banks decline — RRBs and Small Finance Banks may approve | Equitas, Ujjivan, Jana SFB, or nearest RRB |
| Below 600 | Practically very difficult — fix your score first | Fix, then reapply in 3-6 months |
| No credit history (-1 or 0) | Still eligible — especially for Shishu | The bank where you hold your savings account |
What banks actually look at when there is no credit score:
- Six months of bank statement — transaction patterns show income regularity
- Cheque bounce history — even one bounce in six months is a red flag
- Udyam registration — signals genuine business intent
- Quality of project report — a strong DPR compensates for weak credit history
How to improve a low CIBIL score in 3 steps:
Step 1: Get your free annual report at cibil.com — identify every default, no matter how small. Step 2: Settle the smallest defaults first — clearing a Rs.2,000-5,000 bill improves the score faster than you expect. Step 3: Use a secured credit card (against a fixed deposit) for 3-4 months and pay the full balance each month.
Timeline: A score can realistically improve from 620 to 670+ in 3-4 months with disciplined repayment.
Income Proof and ITR — Mandatory or Not?
This is the second most common misconception.
| Category | ITR Required | Minimum Income Proof |
|---|---|---|
| Shishu (up to Rs.50,000) | Not mandatory | Bank statement — even 3 months |
| Kishore (up to Rs.5 lakh) | Not mandatory at most banks | 6 months bank statement + project report |
| Tarun (up to Rs.10 lakh) | Preferred but not always mandatory | 12 months bank statement + project report + business proof |
| Tarun Plus (up to Rs.20 lakh) | Strongly preferred | 12+ months statement + project report + previous Tarun loan closure certificate |
Salaried individuals can apply for a Mudra loan if they have a registered side business. The loan is disbursed to the business account, not the personal salary account.
Who Is NOT Eligible — Clear Boundaries
| Category | Reason |
|---|---|
| Pure crop or plantation farmers | Mudra covers non-farm income only; Kisan Credit Card (KCC) is the right route for crop loans |
| Businesses already classified as NPA | The default must be cleared before applying |
| Large corporations and Public Limited companies | The scheme is for micro and small enterprises only |
| NRIs and foreign nationals | Indian citizenship is required |
| Alcohol production and sales | On the negative list |
| Tobacco and beedi manufacturing | On the negative list |
| Gambling and lottery businesses | On the negative list |
| Slaughterhouses | On the negative list — note that meat retail shops and non-veg restaurants are NOT on the list |
| Businesses needing more than Rs.20 lakh | Beyond the Mudra ceiling — CGTMSE or SIDBI are the right routes |
Important clarification: Non-vegetarian restaurants, chicken shops, and meat retail outlets are NOT on the Mudra negative list. Only slaughterhouses are excluded. A non-veg dhaba owner can apply for a Mudra loan.
Category-Wise Eligibility — Detailed Breakdown
Shishu — Up to Rs.50,000
For brand-new businesses with no track record. Street vendors, roadside shops, micro units starting from scratch. No credit history is acceptable. A basic 1-2 page business summary strengthens the application, though a formal DPR is not mandatory. Processing time: 7-15 days typically.
Kishore — Rs.50,001 to Rs.5 Lakh
For established businesses with one or more years of operations wanting to expand. CIBIL 650 and above preferred. Six months bank statement required. Project report is mandatory for most banks above Rs.2 lakh. Processing time: 15-30 days.
Tarun — Rs.5,00,001 to Rs.10 Lakh
For businesses with a solid track record scaling up significantly. CIBIL 680 and above practically required at PSU banks. Detailed project report with correct DSCR calculation is non-negotiable. Udyam registration required. IT returns preferred. Processing time: 20-45 days.
Build your Tarun project report with guaranteed DSCR 1.25+: mudraready.in/mudra-loan-project-report — Rs.399, first report free.
Tarun Plus — Rs.10,00,001 to Rs.20 Lakh
For entrepreneurs who have already taken and fully repaid a Tarun loan. Introduced October 24, 2024. Tarun loan closure certificate is mandatory — no exceptions. CIBIL 700 and above practically required. Udyam registration mandatory. 100% collateral-free under CGFMU (Credit Guarantee Fund for Micro Units) coverage. Processing time: 30-60 days.
Sector-Wise Eligibility — Specific Businesses Confirmed
Banks occasionally give incorrect information about specific business types. This table clarifies the actual eligibility:
| Business | Eligible | Category | Notes |
|---|---|---|---|
| Kirana / Grocery Store | Yes | Trading | One of the most common Mudra businesses |
| Beauty Parlour | Yes | Service | High approval rate — established income stream |
| Mobile Repair Shop | Yes | Service | Covered under electronics repair |
| Tailoring Unit | Yes | Manufacturing / Service | Both categories apply |
| Coaching Centre | Yes | Service | Education services fully covered |
| Medical Store / Pharmacy | Yes | Trading | FSSAI registration strengthens application |
| Auto-Rickshaw / E-Rickshaw | Yes | Transport | Vehicle purchase financed through Mudra |
| Dairy Farm | Yes | Agriculture-Allied | Not direct crop farming — eligible |
| Poultry Farm | Yes | Agriculture-Allied | NABARD subsidy can also be stacked |
| Flour Mill | Yes | Manufacturing | Food processing category |
| Agarbatti Making | Yes | Manufacturing | Also eligible under PMEGP |
| Restaurant / Dhaba (Veg) | Yes | Service | FSSAI licence mandatory |
| Non-Veg Restaurant (no liquor) | Yes | Service | Meat retail NOT on negative list |
| Tea Stall | Yes | Service | Shishu category ideal for small setup |
| Paper Cup Business | Yes | Manufacturing | PMEGP also applicable |
| Online / E-commerce Business | Yes | Trading / Service | GST registration required |
| Freelancer / IT Services | Yes | Service | Registered business entity needed |
| Alcohol Production or Bar | No | Negative list | Prohibited under PMMY |
| Tobacco Manufacturing | No | Negative list | Prohibited |
| Pure Crop Farming (paddy, wheat) | No | Agriculture — use KCC | Not covered under PMMY |
| Slaughterhouse | No | Negative list | Animal processing is eligible; slaughter is not |
Documents Required — Complete Checklist by Category
| Document | Shishu | Kishore | Tarun | Tarun Plus |
|---|---|---|---|---|
| Aadhaar Card | Required | Required | Required | Required |
| PAN Card | Required | Required | Required | Required |
| 2 Passport Size Photos | Required | Required | Required | Required |
| Bank Statement | 3 months | 6 months | 12 months | 12+ months |
| Business Address Proof | Basic | Required | Required | Required |
| Udyam Registration | Helpful | Recommended | Required | Mandatory |
| Project Report / DPR | Not needed | Recommended | Mandatory | Mandatory |
| SC/ST/OBC Certificate | If applicable | If applicable | If applicable | If applicable |
| Previous Tarun Closure Certificate | Not applicable | Not applicable | Not applicable | Mandatory |
| IT Returns (last 2 years) | Not needed | Helpful | Preferred | Required |
| GST Registration | If registered | If applicable | If applicable | If applicable |
SC/ST Entrepreneurs — Mudra vs PMEGP: Which Is Better?
Mudra loan itself carries no subsidy regardless of category. But if you are SC/ST, a powerful alternative exists that is worth comparing before you apply.
Example — Rs.8 lakh new manufacturing unit, SC/ST applicant, rural area:
| Option | Own Contribution | Government Subsidy | Bank Loan | Monthly EMI (11%, 5 years) |
|---|---|---|---|---|
| Mudra Tarun | Rs.80,000 (10%) | Zero | Rs.7,20,000 | Rs.15,660 |
| PMEGP (35% subsidy, rural SC/ST) | Rs.40,000 (5%) | Rs.2,80,000 — never repay | Rs.4,80,000 | Rs.10,440 |
| PMEGP advantage | Rs.40,000 less upfront | Rs.2,80,000 forgiven | Rs.2,40,000 less debt | Rs.5,220/month saved |
If you are SC/ST and starting a new business — PMEGP is almost always the better route for amounts above Rs.5 lakh. Full guide: mudraready.in/blog/pmegp-loan-kaise-milega-2026
5 Common Eligibility Mistakes — and How to Avoid Them
Mistake 1 — Applying With an Unresolved Default
Rohit from Bhopal applied for Rs.5 lakh Kishore and was rejected. The reason: a Rs.3,200 credit card payment from 2022 showed as a default on his CIBIL report. He had no idea it was there.
The fix: Check your CIBIL report before applying — the free annual report is available at cibil.com. Settle all small defaults before submitting any application.
Mistake 2 — Applying for the Wrong Business Category
Sunita from Coimbatore tried applying for a Mudra loan for her tomato farm. Rejected — pure crop cultivation is not eligible under PMMY.
The fix: Her tomato-based pickle processing unit — food processing from agricultural produce — is fully eligible. Agriculture-allied processing is covered under Mudra; raw crop farming is not.
Mistake 3 — No Project Report for Kishore Applications
Arvind from Patna applied for Rs.3 lakh Kishore for his mobile repair shop expansion and walked into the bank without a project report. The bank officer sent him back.
The fix: For any amount above Rs.50,000, carry a project report. MudraReady generates a bank-ready DPR in under 15 minutes — Rs.399, first report free.
Mistake 4 — Wrong Bank for a Low CIBIL Score
Fatima from Hyderabad had a CIBIL score of 620 and went directly to HDFC Bank, which rejected her immediately. She lost two weeks.
The fix: A score between 600 and 650 requires a different approach. Regional Rural Banks (RRBs) and Small Finance Banks — Equitas, Ujjivan, Jana — have more flexible credit assessment norms. Start there, not with private banks.
Mistake 5 — Requesting Tarun Plus Without Previous Tarun History
Deepak from Surat walked into SBI asking for Rs.15 lakh under Tarun Plus. It was his first business loan ever.
The fix: Tarun Plus is exclusively for borrowers who have already taken and fully repaid a Tarun category loan. First-time borrowers can apply for up to Rs.10 lakh under Tarun, repay it with a clean record, and then become eligible for Tarun Plus.
How to Apply for a Mudra Loan — Online and Offline
Online — Faster and Multi-Lender
jansamarth.in is the government's official Mudra loan portal. Register with your mobile number, fill in business details, select your category, upload documents, and receive an in-principle approval. Over 254 lenders are connected — this gives significantly better chances than approaching a single bank.
Offline — Relationship-Based
Go to the branch where you hold your savings or current account first. Your existing banking relationship improves your chances. Ask specifically for "Mudra Kishore" or "Mudra Tarun" — use the exact scheme name. Approach the MSME counter or branch manager directly, not the general banking counter. Follow up every 5-7 days — files with regular follow-up get processed faster.
DSCR — The Hidden Eligibility Factor for Kishore and Tarun
Beyond basic eligibility, banks run a DSCR check on your project report for Kishore and Tarun categories.
DSCR = (Net Annual Profit + Depreciation + Interest) ÷ (Annual EMI + Interest)
Minimum DSCR required:
- Service businesses: 1.25
- Manufacturing businesses: 1.50
A DSCR below the minimum means rejection — regardless of a perfect CIBIL score and clean documents.
Check your DSCR before applying: mudraready.in/dscr-calculator
Build your project report with DSCR guaranteed at 1.25 and above: mudraready.in/mudra-loan-project-report — Rs.399, first report free.
Mudra Loan vs PMEGP vs Stand Up India — Quick Eligibility Comparison
| Parameter | Mudra Loan | PMEGP | Stand Up India |
|---|---|---|---|
| Who Can Apply | Any Indian 18-65, non-farm business | New business owners only | SC/ST and women only |
| Maximum Loan | Rs.20 lakh (Tarun Plus) | Rs.50 lakh manufacturing, Rs.20 lakh service | Rs.10 lakh to Rs.1 crore |
| Government Subsidy | None | 15% to 35% — never repaid | None |
| Business Stage | New or existing | New businesses only | New businesses only |
| Best Suited For | Quick collateral-free loan, any business stage | Maximum benefit on a new business | Large collateral-free loans for SC/ST and women |
Full comparison: mudraready.in/blog/mudra-vs-pmegp-vs-cgtmse-vs-stand-up-india
Frequently Asked Questions — Mudra Loan Eligibility 2026
Q1. What is the eligibility criteria for Mudra loan in 2026? The basic eligibility for a Mudra loan in 2026 is: Indian citizen, age 18-65, running or planning a non-farm business in manufacturing, trading, services, or agriculture-allied activities, and no active loan defaults. There are four categories — Shishu up to Rs.50,000, Kishore up to Rs.5 lakh, Tarun up to Rs.10 lakh, and Tarun Plus up to Rs.20 lakh, with Tarun Plus exclusively available to those who have already repaid a Tarun loan. Apply online at jansamarth.in or visit your nearest bank branch with a completed project report.
Q2. Is there a minimum CIBIL score required for a Mudra loan? Officially, PMMY does not mandate a minimum CIBIL score. However, individual banks apply their own credit assessment. In practice, a score of 650 and above significantly improves approval chances. A score of 700 and above gets smooth approval at most PSU banks. If you have no credit history at all — score of -1 or 0 — you can still qualify, particularly for Shishu, especially at the bank where you already hold your savings account. Scores below 600 make approval very difficult at PSU banks; try RRBs or Small Finance Banks instead.
Q3. Can a home-based business apply for a Mudra loan? Yes — a home-based business is fully eligible. Your residential address can serve as the business address. Utility bills in your name at that address work as proof. You are not required to have a commercial space or trade license for smaller amounts. For Kishore and above, Udyam registration at your home address strengthens the application considerably.
Q4. Can a salaried employee apply for a Mudra loan? Yes — a salaried person can apply if they have a registered side business. The loan is disbursed to the business account, not the personal salary account. Udyam registration and a separate current account for the business are recommended to demonstrate genuine business activity. For amounts of Rs.3-5 lakh, banks are generally comfortable with salaried applicants who have a documented side business.
Q5. Is agriculture eligible for a Mudra loan? Direct crop cultivation — growing paddy, wheat, vegetables for sale — is not eligible. The Kisan Credit Card (KCC) is the correct product for crop loans. However, agriculture-allied activities are fully eligible: dairy farming, poultry, fishery, beekeeping, and food processing like flour milling, rice milling, oil extraction, pickle making, and agro-processing are all covered under PMMY. If your business involves processing or value-adding to agricultural produce, confirm with your bank.
Q6. What is Mudra Tarun Plus and who can apply? Tarun Plus was introduced in Union Budget 2024-25 and made operational on October 24, 2024. It allows loans of Rs.10 lakh to Rs.20 lakh — the highest tier under Mudra. It is exclusively for entrepreneurs who have previously availed and fully repaid a Tarun category loan (Rs.5-10 lakh). You will need the closure certificate from the previous Tarun loan. First-time borrowers cannot apply for Tarun Plus — there are no exceptions. The loan is 100% collateral-free, covered under CGFMU.
Q7. Does a Mudra loan benefit SC/ST applicants more than general category? The Mudra loan itself has identical terms regardless of category — no additional subsidy for SC/ST. However, if you are SC/ST and starting a new business, PMEGP offers 35% subsidy in rural areas — meaning up to Rs.17.5 lakh on a Rs.50 lakh project is forgiven and never repaid. On a smaller Rs.8 lakh project, PMEGP saves Rs.5,220 per month on EMI compared to Mudra. If you are SC/ST and the business is new, compare PMEGP carefully before defaulting to Mudra. Full guide: mudraready.in/blog/pmegp-loan-kaise-milega-2026
Q8. Can an existing business apply for a Mudra loan to expand? Yes — this is one of the primary use cases for Kishore and Tarun. Existing businesses wanting to buy new equipment, expand to a second location, add working capital, or upgrade technology are exactly who these categories serve. Only PMEGP is restricted to new businesses — Mudra has no such restriction. An existing business with clean repayment history and Udyam registration has very strong approval prospects.
Q9. How long does Mudra loan approval take after submitting? Shishu approvals typically take 7-15 days. Kishore takes 15-30 days. Tarun takes 20-45 days. Tarun Plus takes 30-60 days due to more thorough credit assessment. The biggest delays come from incomplete documents or a weak project report that the bank sends back. Online applications through jansamarth.in often receive in-principle approval within 2-7 days, with the physical processing completing at the bank level afterwards.
Q10. If a Mudra loan is rejected, can I reapply? Yes — there is no permanent blacklist under PMMY. A rejection from one bank does not affect your eligibility at another. The most important step after rejection is to get the specific reason in writing from the bank officer. The most common fixable reasons are: low CIBIL score (resolve defaults, wait 3-4 months), weak project report (rebuild with correct DSCR using MudraReady), unrealistic income projections (start Year 1 at 50-60% capacity), and wrong bank selection (if a private bank declined, try a PSU bank or RRB). Full rejection guide: mudraready.in/blog/mudra-loan-reject-kyu-hota-hai
Meera Joshi Today — and Your Next Step
Meera's tailoring unit is running in Nashik today. No CIBIL score, no ITR, home-based business — and the loan came through in 19 days. Because eligibility is a simple checklist: Indian citizen, age 18-65, non-farm business, no defaults.
Everything else — CIBIL score, ITR, income proof — is bank-level assessment, not a government mandate.
Your next step is straightforward:
- Check your CIBIL score: cibil.com — free annual report
- Complete Udyam registration: udyamregistration.gov.in — free, 10 minutes
- Build your project report: mudraready.in/mudra-loan-project-report — Rs.399, first report free
- Apply online: jansamarth.in — fastest route to multiple lenders
Build your bank-ready Mudra loan project report in 10 minutes. Rs.399. First report completely free.
Related Guides
- Mudra Loan Project Report — How to Build One
- Why Mudra Loan Gets Rejected — 7 Reasons and Fixes
- PMEGP Loan — Better Option for SC/ST and Women Starting New Businesses
- DSCR — What It Is and Why Banks Use It
- CGTMSE — Collateral Free Loan for Larger Amounts
- Stand Up India — Rs.1 Crore for SC/ST and Women
- DSCR Calculator
- EMI Calculator
- Mudra vs PMEGP vs CGTMSE — Full Comparison
- Apply Online: jansamarth.in
- Udyam Registration: udyamregistration.gov.in
Sources
- PMMY Official Portal: mudra.org.in
- PIB — Tarun Plus announcement July 2024, operationalised October 2024: pib.gov.in
- RBI MSME Lending Directions 2026: rbi.org.in
- MUDRA Annual Report 2024-25 — 52 crore+ accounts, Rs.32 lakh crore disbursed
- MSMEGyan Mudra Eligibility Guide — last verified April 2026
Last Updated: August 2026
Ready to Apply for your Business Loan?
Most banks reject loans due to incorrect project reports. Create a professional, bank-compliant project report in just 5 minutes with MudraReady.
